
Minerals and Metal Market Trends, Demand, Growth & Future Outlook 2026–2034
Minerals and Metal Market Size
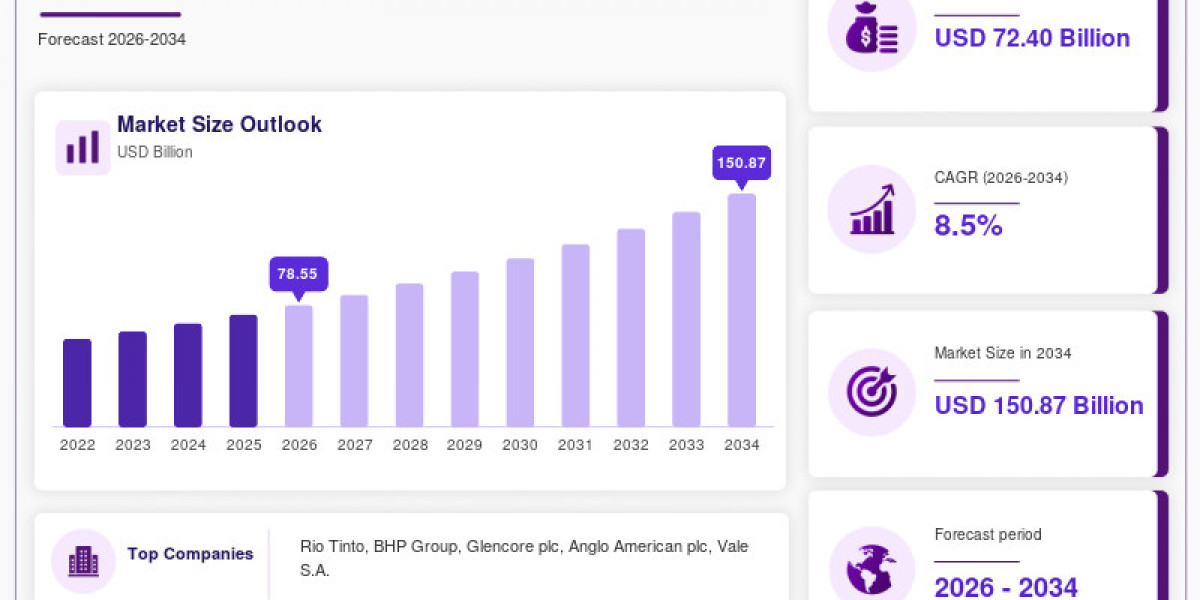
The global Minerals and Metal Market was valued at USD 72.40 billion in 2025 and is projected to grow from USD 78.55 billion in 2026 to USD 150.20 billion by 2034, registering a CAGR of 8.5% during the forecast period from 2026 to 2034.
The minerals and metal industry covers the extraction, processing, refining, trading, and supply of metallic and selected industrial mineral commodities used across global industrial and commercial value chains. Key participants include mining companies, mineral processors, smelters, refiners, commodity traders, recyclers, and manufacturers.
Market growth is supported by infrastructure development, industrialization, electrification, renewable energy deployment, advanced manufacturing, and increasing demand for materials used in batteries, electricity grids, vehicles, and electronic devices. Copper and aluminium remain essential industrial inputs, while lithium, nickel, cobalt, graphite, rare earth elements, and other critical minerals are becoming increasingly important to strategic supply-chain planning.
Key Takeaways
Market Size in 2026: USD 78.55 billion.
Market Size by 2034: USD 150.20 billion.
CAGR (2026–2034): 8.5%.
Dominant Product Type: Base Metals, accounting for approximately 42.3% of the market according to the supplied market assessment.
Dominant Region: Asia Pacific, with an estimated 38.5% share of global market revenue.
Key Growth Factors: Infrastructure development, energy transition, electrification, advanced manufacturing, and strategic investment in mineral supply chains.
Major Opportunities: Critical mineral production, metal recycling, advanced processing technologies, and regional supply-chain development.
Request a Sample
https://reedintelligence.com/market-analysis/minerals-and-metal-market/request-sample
Minerals and Metal Market Trends
The minerals and metal market is evolving as industries prioritize reliable material supplies, resource efficiency, and the transition toward lower-carbon technologies. Demand for traditional industrial metals continues to be influenced by construction, transportation, manufacturing, and infrastructure investment. At the same time, critical minerals are gaining strategic importance because of their role in batteries, renewable energy equipment, electric vehicles, and advanced electronics.
Another significant trend is the diversification of mineral supply chains. Governments and manufacturers are increasingly considering domestic production, alternative sourcing arrangements, recycling, and long-term procurement agreements to reduce exposure to concentrated suppliers and international trade disruptions.
Digital mining and advanced mineral processing are also gaining attention. Automation, artificial intelligence, remote sensing, and predictive maintenance can help mining companies improve productivity, monitor equipment, and optimize resource recovery. These technologies are becoming relevant to operational efficiency and long-term competitiveness.
Minerals and Metal Market Drivers
Infrastructure Development and Industrialization
Expanding transportation networks, urban development, housing, industrial facilities, and electricity infrastructure support demand for metals and minerals. Copper, aluminium, zinc, and other industrial materials are essential for construction, machinery, electrical systems, and large-scale infrastructure projects. Continued infrastructure investment creates demand across mining, processing, distribution, and manufacturing activities.
Energy Transition and Electrification
Renewable energy installations, electric vehicles, battery storage, charging infrastructure, and electricity grids require substantial quantities of selected metals and minerals. Copper, aluminium, lithium, nickel, graphite, and rare earth elements are particularly important to these applications. As energy systems become more electrified, producers with competitive resources and dependable supply chains can benefit from growing material requirements.
Growth in Advanced Manufacturing and Digital Infrastructure
Data centers, artificial intelligence infrastructure, telecommunications networks, semiconductors, and advanced electronic equipment are increasing demand for electrical conductors, specialized metals, and critical minerals. Copper and aluminium support electrical systems, while precious metals and selected specialty materials are used in electronic components and high-performance applications.
Strategic Investment in Mineral Supply Chains
Governments and manufacturers are increasingly prioritizing domestic production, diversified sourcing, recycling, and long-term mineral procurement. Policies and investments intended to strengthen supply security are encouraging exploration, mining, processing, refining, and recycling projects. These initiatives create opportunities for producers that can supply materials reliably and meet customer requirements.
Minerals and Metal Market Restraints
Commodity Price Volatility
Mineral and metal prices can fluctuate considerably due to changes in industrial demand, interest rates, exchange rates, trade policy, inventory levels, and geopolitical conditions. Price volatility can affect operating margins, investment decisions, and the economic viability of new mining projects. Companies must manage market exposure while balancing production costs and long-term investment commitments.
High Capital Requirements
Exploration, mine development, mineral processing, smelting, and refining require significant upfront investment. Projects may involve long development periods, financing constraints, cost overruns, and uncertainty regarding future commodity prices. These factors can delay capacity expansion and create barriers for new market participants.
Environmental and Regulatory Requirements
Mining and mineral processing can affect land, water resources, biodiversity, and surrounding communities. Environmental approvals, permitting requirements, emissions controls, waste management, and rehabilitation obligations can increase project costs and extend development timelines. Producers must account for these requirements when planning operations and developing new resources.
Supply-Chain Concentration and Geopolitical Risks
The production and refining of several critical minerals are concentrated in a limited number of countries. Export controls, trade restrictions, political instability, transportation disruptions, and changes in international relations can affect material availability and prices. Supply-chain diversification and investment in alternative sources are therefore important considerations for manufacturers and governments.
Minerals and Metal Market Opportunities
Expansion of Critical Mineral Production
Investment in copper, lithium, nickel, graphite, rare earth elements, and other strategic materials offers opportunities to meet demand from electrification, energy storage, advanced manufacturing, and other strategic applications. New discoveries, mine expansions, and the development of existing resources can help diversify supply and support downstream industries.
Recycling and Circular Material Supply
Recycling metals from industrial scrap, end-of-life vehicles, electronics, batteries, and construction materials can reduce dependence on primary extraction. Improved collection systems, sorting technologies, and recovery processes create opportunities for secondary material producers and integrated recycling businesses. Recovered materials can also support manufacturers seeking more resource-efficient supply chains.
Advanced Processing and Digital Mining
Automation, artificial intelligence, remote sensing, predictive maintenance, and advanced mineral-processing techniques offer opportunities to improve operating efficiency and resource recovery. Companies adopting these technologies may be able to optimize production, monitor equipment performance, manage costs, and extract greater value from existing assets.
Strategic Partnerships and Regional Supply Chains
Partnerships among mining companies, governments, manufacturers, financial institutions, and technology providers can support project financing, downstream processing, and long-term material offtake. Regional processing capacity and diversified sourcing arrangements offer opportunities to improve supply-chain resilience and strengthen connections between resource producers and industrial customers.
Minerals and Metal Market Segmentation Analysis
By Product Type
Base Metals dominate the market, accounting for approximately 42.3% of market revenue according to the supplied market-specific assessment. Copper, aluminium, zinc, nickel, lead, and related materials are widely used in construction, transportation, electrical infrastructure, industrial machinery, and manufacturing. Their broad industrial applications and established supply chains support demand across mature and emerging economies.
Critical Minerals are strategically important because of their applications in batteries, renewable energy systems, electric vehicles, advanced electronics, and other industrial technologies. Supply-chain diversification and electrification are reinforcing their importance. However, the supplied data does not establish a comparable, independently verified fastest-growing product category or segment-specific CAGR.
Precious Metals support jewelry, investment, electronics, and specialized industrial applications. Industrial Minerals are used in construction materials, ceramics, glass, chemicals, agriculture, and other manufacturing processes. Demand for these categories depends on industrial activity, regional investment, end-use requirements, and raw-material availability.
By Application
Construction is a major application area because buildings, bridges, roads, transport networks, water infrastructure, and industrial facilities require substantial quantities of metals and mineral-based materials. Copper, aluminium, zinc, and other industrial inputs support electrical connectivity, structural components, equipment, and infrastructure systems.
Electrical and Electronics applications are becoming increasingly important due to demand for power distribution, telecommunications, semiconductors, data centers, consumer electronics, and digital infrastructure. Copper and aluminium are important for electrical systems, while selected precious and critical metals are used in specialized components.
Energy and Power offer opportunities as electricity grids, renewable energy installations, energy storage, and electrification projects expand. Automotive and industrial manufacturing also contribute to material demand through vehicle production, machinery, equipment, tools, and industrial systems.
The available market-specific information does not provide a verified dominant application share or comparable fastest-growing application CAGR. Assigning precise percentages or rankings to these applications would therefore be speculative.
By End User
Manufacturing is a major end-user category because minerals and metals are essential inputs for machinery, industrial equipment, electrical systems, vehicles, consumer products, and fabricated components. Manufacturers depend on consistent material quality, reliable supply, and competitive input costs.
Infrastructure and Energy end users require metals for electricity networks, transportation projects, buildings, renewable energy facilities, and industrial infrastructure. Demand is influenced by investment cycles, government spending, electricity requirements, and project financing.
Transportation and Consumer Goods contribute to market demand through vehicles, rail systems, appliances, electronics, and durable products. Recycled metals are also becoming relevant as manufacturers seek to improve resource efficiency and reduce exposure to material-supply risks.
The fastest-growing end-user category and its CAGR cannot be reliably determined from the supplied market-specific dataset. Growth varies by commodity and end-use industry.
Minerals and Metal Market Regional Analysis
Asia Pacific Minerals and Metal Market
Asia Pacific is the dominant region in the minerals and metal market, accounting for approximately 38.5% of global revenue according to the supplied market-specific assessment. Applying this share to the 2025 global market value of USD 72.40 billion produces an indicative regional value of approximately USD 27.87 billion in 2025. This is a calculated estimate based on the stated share, rather than a separately reported regional revenue figure.
The region's position is supported by industrial manufacturing, infrastructure development, construction, transportation, electrical equipment production, and demand for materials used in energy and digital technologies. Its importance to mineral processing and manufacturing supply chains also makes reliable material sourcing a strategic consideration for regional industries.
North America Minerals and Metal Market
North America is an important market because of its industrial manufacturing base, infrastructure requirements, automotive sector, energy investments, and strategic interest in critical mineral supplies. The United States and Canada have mineral resources, established metals producers, and demand from construction, electrical infrastructure, and industrial applications.
Investment in supply-chain resilience, mineral recycling, and domestic production of materials used in batteries, electronics, defense systems, and clean-energy technologies is creating opportunities for producers and processors. However, a compatible regional market-share percentage and 2025 market value have not been independently verified against the supplied global market definition.
Europe Minerals and Metal Market
Europe has a developed metals and manufacturing sector supported by automotive production, industrial machinery, construction, electrical equipment, and renewable energy deployment. Demand is also influenced by decarbonization initiatives, power-grid upgrades, transportation electrification, and the need for reliable critical raw-material supplies.
The region faces challenges associated with energy costs, industrial competitiveness, import dependence, and the concentration of mineral processing in other markets. These conditions encourage investment in recycling, strategic sourcing, resource efficiency, and diversified supply chains. A comparable regional share and market value are not verified in the supplied dataset.
Latin America Minerals and Metal Market
Latin America is an important source of mineral resources, including copper, lithium, iron ore, silver, and other industrial materials. Chile and Peru are significant participants in copper production, while Argentina and Chile contribute to lithium supply chains. Brazil also has substantial mineral production and processing capabilities.
The region offers opportunities for new mining projects, downstream processing, infrastructure investment, and integration into diversified global supply chains. Long-term development depends on financing, permitting, transport and energy infrastructure, environmental management, and stable investment frameworks. A compatible regional market share and market value are not established by the supplied data.
Middle East and Africa Minerals and Metal Market
The Middle East and Africa region offers opportunities linked to infrastructure development, construction, industrial diversification, mining investment, and energy-related projects. Several African economies possess significant mineral resources, while Middle Eastern countries are investing in industrial development, metals production, and supply-chain diversification.
Demand is influenced by urbanization, transportation and power infrastructure, manufacturing, and large-scale development programs. Opportunities also exist in mineral beneficiation, refining, recycling, and domestic processing. Market development varies across countries because of differences in resource availability, infrastructure, regulation, financing, and industrial demand.
Minerals and Metal Market Competitive Landscape
The minerals and metal market is competitive, with diversified mining groups, commodity producers, metal processors, refiners, and specialized mineral companies operating across the value chain. Competition is influenced by access to high-quality deposits, operating efficiency, production scale, commodity diversification, customer contracts, technological capabilities, and capital allocation.
Major companies are positioning their portfolios to serve both established industrial markets and growing demand for materials used in electrification and advanced manufacturing. Investment in copper, lithium, and other strategic resources is an important part of this evolving competitive environment. Recycling, processing efficiency, and supply-chain partnerships also provide ways to strengthen market positions.
Key Market Players
Key companies identified in the supplied market information include:
Rio Tinto
BHP Group
Glencore plc
Anglo American plc
Vale S.A.
Freeport-McMoRan Inc.
Southern Copper Corporation
Newmont Corporation
Barrick Mining Corporation
Antofagasta plc
Teck Resources Limited
Minerals and Metal Market Recent Developments
October 2026 – Glencore's Agua Rica/MARA Project: According to the supplied report, Glencore announced that its MARA project in Argentina had received approval under the Incentive Regime for Large Investments. The company also reported progress toward restarting Alumbrera, with first production expected in the second half of 2027. The development represents a milestone for future copper production and regional mineral investment. Source: https://www.glencore.com/media-and-insights/news/glencore-receives-rigi-approval-for-agua-rica--mara
September 2026 – Strategic Critical Minerals Reserve Initiative: Glencore announced its selection as a founding partner in VaultCo, a U.S. strategic critical minerals reserve initiative supported by the Export-Import Bank of the United States. The supplied information describes a USD 500 million critical minerals commitment intended to strengthen supply-chain resilience and improve access to critical minerals and base metals for U.S. industry. Source: https://www.glencore.com/media-and-insights/news/glencore-partners-with-us-exim-bank-to-build-strategic-minerals-reserve-fund
Minerals and Metal Market Segments
By Product Type
Base Metals
Precious Metals
Industrial Minerals
Critical Minerals
Others
By Application
Construction
Automotive
Electrical & Electronics
Energy & Power
Industrial Manufacturing
Transportation
Others
By End User
Manufacturing
Infrastructure
Energy
Transportation
Consumer Goods
Others
By Region
North America
Europe
Asia Pacific
Middle East & Africa
Latin America
Frequently Asked Questions
What is the current size of the Minerals and Metal Market?
The global minerals and metal market is projected to reach USD 78.55 billion in 2026, increasing from USD 72.40 billion in 2025.
What will the Minerals and Metal Market be worth by 2034?
The market is projected to reach USD 150.20 billion by 2034.
What is the expected CAGR of the Minerals and Metal Market?
The market is forecast to register a CAGR of 8.5% during the 2026–2034 forecast period.
Which product category dominates the Minerals and Metal Market?
Base Metals is the dominant product category, accounting for approximately 42.3% of the market according to the supplied market-specific assessment.
Which region dominates the Minerals and Metal Market?
Asia Pacific is the dominant region, with an estimated 38.5% share of global revenue according to the supplied market assessment.
What are the major factors driving the Minerals and Metal Market?
Major drivers include infrastructure development, industrialization, energy transition, electrification, advanced manufacturing, digital infrastructure, and strategic investment in mineral supply chains.
Who are the key players in the Minerals and Metal Market?
Major companies include Rio Tinto, BHP Group, Glencore plc, Anglo American plc, Vale S.A., Freeport-McMoRan Inc., Southern Copper Corporation, Newmont Corporation, Barrick Mining Corporation, Antofagasta plc, and Teck Resources Limited.
Conclusion
The minerals and metal market is expected to expand as infrastructure development, industrial manufacturing, electrification, and investment in energy and digital technologies support demand for a broad range of materials. Base metals remain important to established industrial value chains, while critical minerals are gaining strategic relevance as manufacturers and governments seek dependable supplies.
At the same time, commodity price volatility, high capital requirements, environmental obligations, and concentrated supply chains remain important challenges. Opportunities in recycling, advanced processing, digital mining, and regional supply-chain development may help industry participants improve efficiency and resilience. With the market projected to reach USD 150.20 billion by 2034 at a CAGR of 8.5%, investment decisions will continue to depend on material demand, project economics, supply security, and the ability to operate efficiently.
Full Report
https://reedintelligence.com/market-analysis/minerals-and-metal-market